Mindspace Business Parks REIT posted a sharp improvement in second-quarter earnings, underlining that demand for high-quality office space is still translating into stronger cash generation even in a patchy leasing market.
Mindspace Business Parks REIT Q2 NOI, DPU Rise
Net operating income rose 31.9% from a year earlier to Rs 836 crore, while revenue from operations increased 29.8% to Rs 1,010 crore. The trust also said it leased 1.6 million sq ft in the quarter, including about 0.6 million sq ft at newly acquired Chennai assets and a 0.5 million sq ft transaction at One Radial with a European banking, financial services and insurance global capability centre. For investors, the mix matters: large, sticky occupiers are typically the kind of tenants that support occupancy, rent visibility and valuation stability in listed office assets.
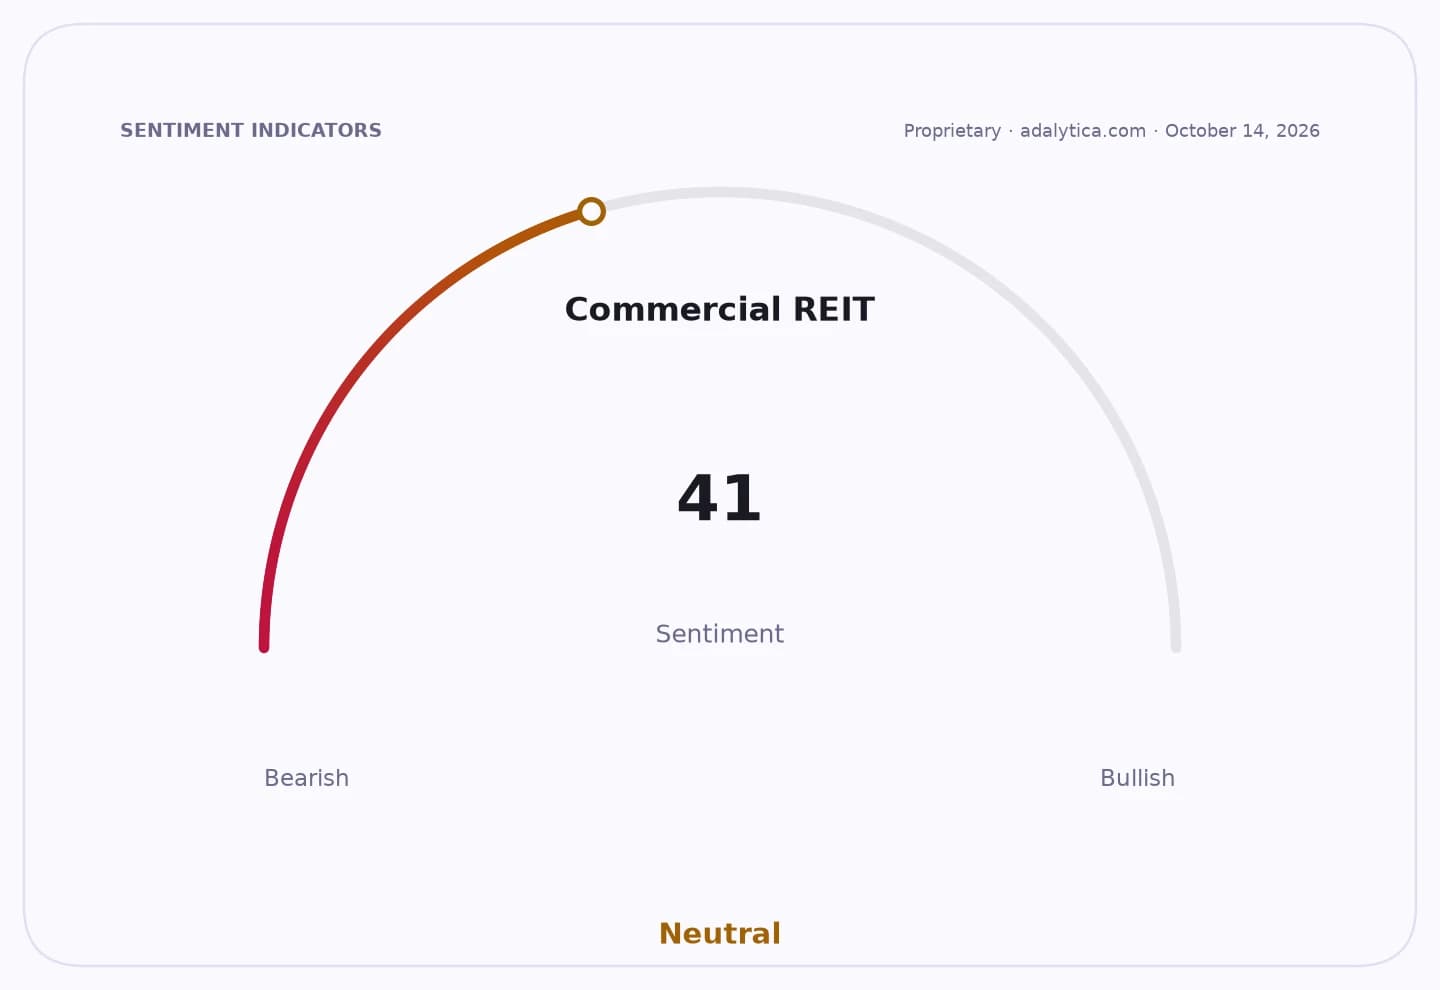
Sentiment Indicators
On a like-to-like basis, excluding assets bought in the first half of the financial year, NOI still grew 16.8%, suggesting the improvement was not just a function of acquisitions. That is important because it indicates healthier underlying demand across the existing portfolio, not merely balance-sheet expansion. The trust’s distribution per unit rose 14.4% to Rs 6.67, or about Rs 442 crore in total, giving unitholders a direct cash-flow lift that should help sustain investor appetite for REIT payouts.
The portfolio metrics also point to a relatively disciplined capital structure. Loan-to-value remained broadly unchanged at 29.1%, and the cost of debt was 7.43% per annum, levels that leave Mindspace with room to fund growth without materially stretching leverage. In a higher-rate environment, stable borrowing costs and moderate gearing are key supports for distributable income and for the market’s willingness to pay up for yield.
The leasing backdrop remains uneven. Broader office markets have been under regulatory and structural pressure, including tighter tenant-protection rules and a slowdown in new leasing contracts, even as quality office demand has held up better than the headline numbers suggest. That makes Mindspace’s performance more relevant to the sector: it is benefiting from the continuing preference among multinationals and GCCs for large, compliant campuses in Mumbai, Pune, Hyderabad and Chennai.
With 46.4 million sq ft in the portfolio, including 37.7 million sq ft completed and another 8.7 million sq ft under construction or planned, execution on occupancy and rentals will determine whether the current earnings momentum can extend into the next few quarters. The bull case is that sustained demand from global occupiers keeps absorption high and supports further distribution growth; the bear case is that a softer hiring cycle or slower deal closures could moderate leasing momentum. For now, the quarter suggests Mindspace is capturing the better end of the office market.
| Entity | Gains | Losses |
|---|---|---|
| Mindspace REIT | ▲Higher NOI and DPU | ▼— |
| Unitholders | ▲Larger cash distribution | ▼Yield risk if leasing slows |
| GCC tenants | ▲Large, ready office space | ▼Higher occupancy bargaining power |
| Office peers with weaker portfolios | ▲— | ▼Relative leasing and income gap |