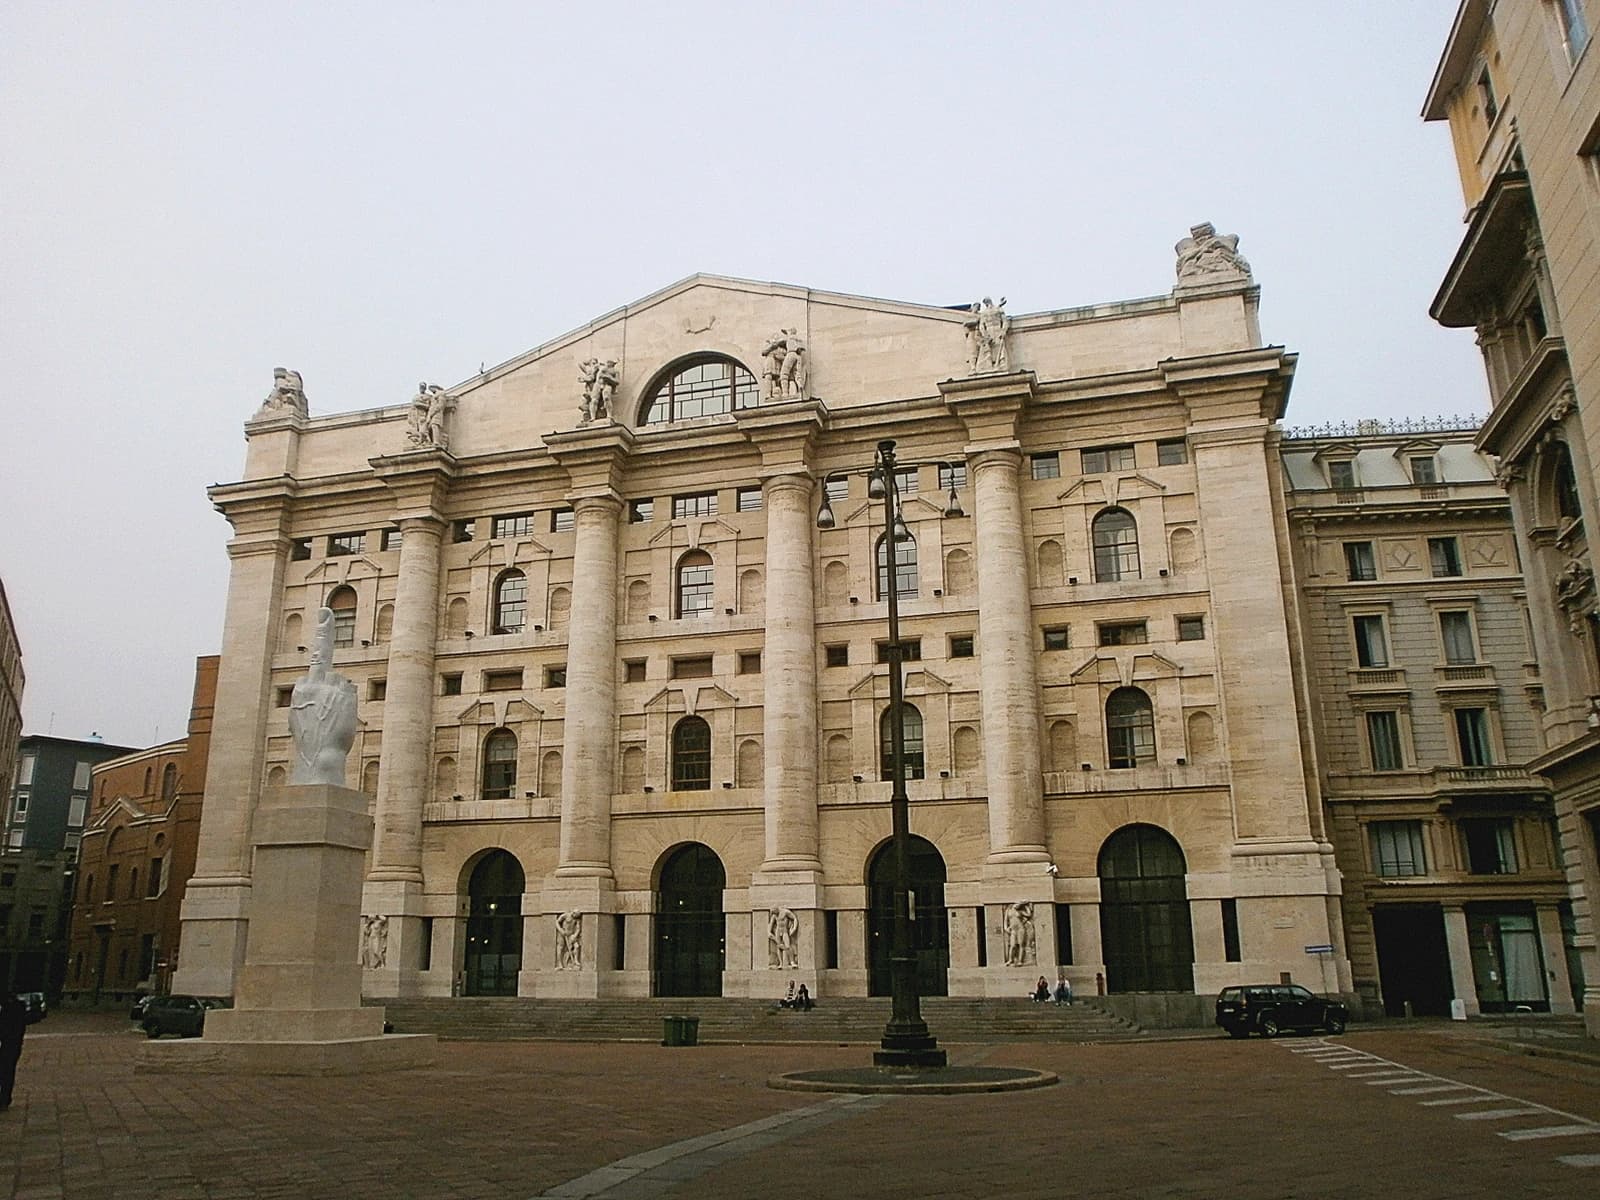
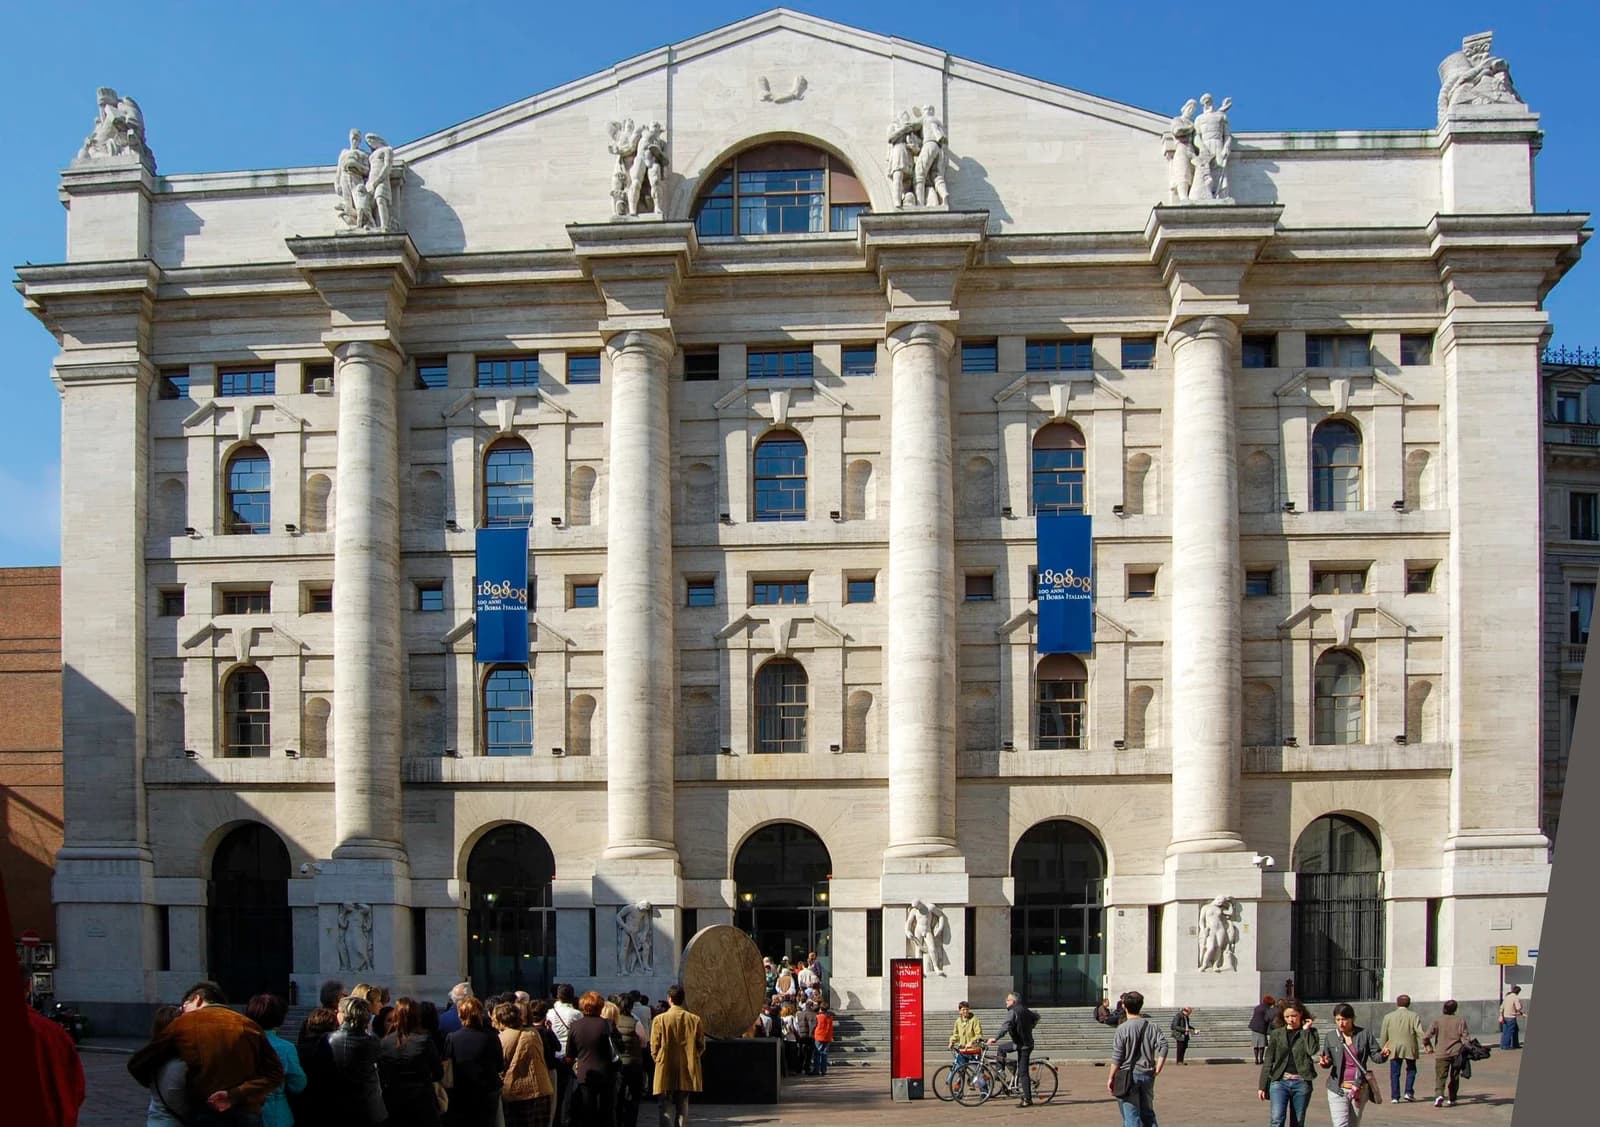
Piazza Affari edged higher on Thursday as a drop in Italy’s borrowing premium over Germany and gains in cyclicals and consumer names outweighed weakness in utilities and some banks. The FTSE Mib rose 0.5% to 46,748 points, while the spread between 10-year BTPs and Bunds narrowed to 116.3 basis points, a sign that investors were slightly more comfortable holding Italian assets even as global rate and commodity signals remained mixed.
Italy Stocks Rise as BTP-Bund Spread Narrows
The move matters because Italy’s market has been sensitive to both sovereign-risk perceptions and sector rotation, and a tighter spread tends to support domestic financial conditions. A lower gap between Italian and German debt usually eases pressure on the state’s refinancing costs and can improve sentiment toward banks, which hold large portfolios of sovereign bonds and are exposed to the domestic funding backdrop.
Sentiment Indicators
Buzzi was the day’s standout, rising 3.86% and outperforming European peers after a recent UBS sector note lifted the building materials group and the broader cement and construction space. Lottomatica added 2.85% ahead of quarterly results, with the stock extending a strong year-to-date run of more than 19%. Investors are treating the name as a proxy for resilient gaming demand and earnings momentum, but the market is also expecting confirmation that recent share gains are backed by cash generation rather than just multiple expansion.
A2a slipped 1.85% in heavy trading, with volumes more than nine times its monthly average, suggesting either a large repositioning by institutional investors or a market reaction to sector-specific flows. Utilities were broadly weaker: Terna fell 0.65%, Enel 0.5% and Prysmian 0.36%. The retreat came as oil prices fell sharply, with WTI down 4.12% to $99.82 a barrel, pressuring energy-linked names such as Eni, which lost 0.95%.
Banks were mixed. UniCredit gained 1.1%, Bper 1.05%, Intesa Sanpaolo 0.7% and Monte dei Paschi 0.65%, while Mediobanca slipped 0.1% and Banco Bpm lost 0.8%. That split underscores a market still differentiating between lenders with stronger earnings visibility and those seen as more exposed to funding or strategic uncertainty. For investors, the key question is whether the recent softness in Italian sovereign yields can keep supporting bank valuations, or whether the sector will again be driven by idiosyncratic deal and capital-return stories.
Elsewhere, mid-cap Landi Renzo jumped 23.84% after approval of its restructuring plan, while Sogefi advanced 7.24%. Those moves show the market is still rewarding balance-sheet repair and turnaround optionality, even in a session dominated by blue-chip rotation.
For now, the broader narrative is one of cautious risk appetite: Italian equities are finding support from lower spreads and stock-specific catalysts, but the market is not moving in unison. The next test will be earnings, especially from names like Lottomatica, and whether further declines in sovereign yields can translate into a more durable re-rating for domestic cyclicals and banks.
| Entity | Gains | Losses |
|---|---|---|
| Italian equities | ▲Softer sovereign risk premium | ▼Broad conviction remains limited |
| Buzzi | ▲UBS-driven sector support | ▼Construction peers lag |
| Lottomatica | ▲Pre-earnings momentum | ▼Valuation must be justified |
| Banks vs utilities | ▲Banks gain from tighter spread | ▼Utilities hit by weaker oil and rotation |