Indonesia’s government paid IDR 394.2 trillion in debt interest through August, underscoring how elevated borrowing costs are eating into fiscal room just as investors are paying closer attention to sovereign debt sustainability.
Indonesia debt interest payments rise to IDR 394.2T
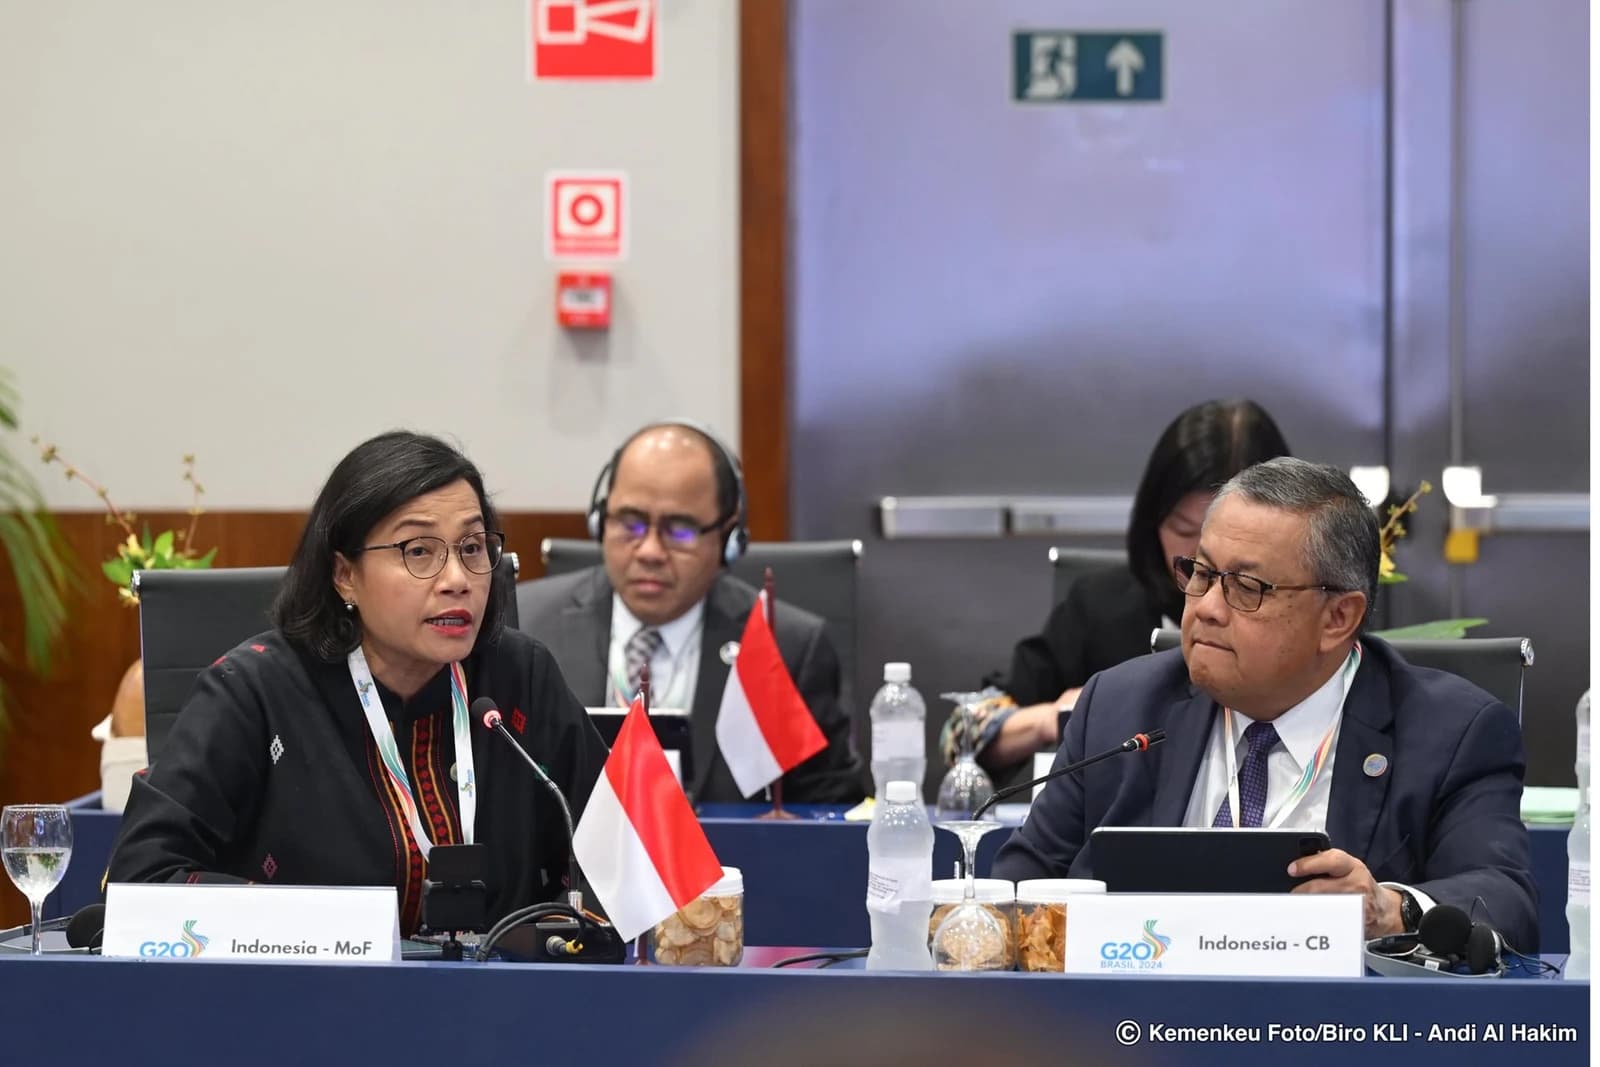
The bill matters because interest expense is a fixed claim on state revenue: every rupiah used to service debt is a rupiah that cannot be spent on infrastructure, social programs or growth support. With global yields still elevated, the cost of rolling and refinancing debt has become a more important part of the fiscal story in emerging markets, including Indonesia.
The latest payments come against a backdrop of stubbornly high benchmark rates globally. The US 10-year Treasury yield was around 5%, while the 2-year note was near 4.8%, levels that keep financing conditions tight and reinforce pressure on sovereign borrowers worldwide. In that environment, even countries with relatively stable market access can see interest costs rise faster than revenues.
For investors, the key issue is not just the size of the interest bill but the trajectory. Rising debt-service costs can narrow policy flexibility, weigh on deficit management and force governments to rely more heavily on issuance at less favorable yields. That can matter for local bond demand, currency stability and the pricing of Indonesian risk relative to peers.
The broader narrative is that higher-for-longer rates are shifting attention from growth plans to balance-sheet discipline. Indonesia’s debt servicing figures fit a global pattern in which governments from Europe to Asia are confronting the same problem: more expensive money means more expensive debt, and that raises the stakes for every budget decision.
The next market focus will be whether financing costs ease if global yields soften, or whether Indonesia has to keep absorbing a heavier interest burden into 2027 budget planning.
| Entity | Gains | Losses |
|---|---|---|
| Indonesian bondholders | ▲Steady interest payments | ▼Lower fiscal flexibility |
| Indonesian government | ▲Continued market access | ▼Rising debt-service burden |
| Investors in local debt | ▲Higher carry yields | ▼Greater sovereign cost pressure |
| Public spending priorities | ▲None | ▼Less room for infrastructure and social outlays |



