Australia is being pressed to keep borrowing costs elevated and cut spending, as a fresh fuel-price shock and stubborn cost pressures threaten to prolong the country’s five-year inflation fight.
Australia inflation pressures keep RBA rates elevated
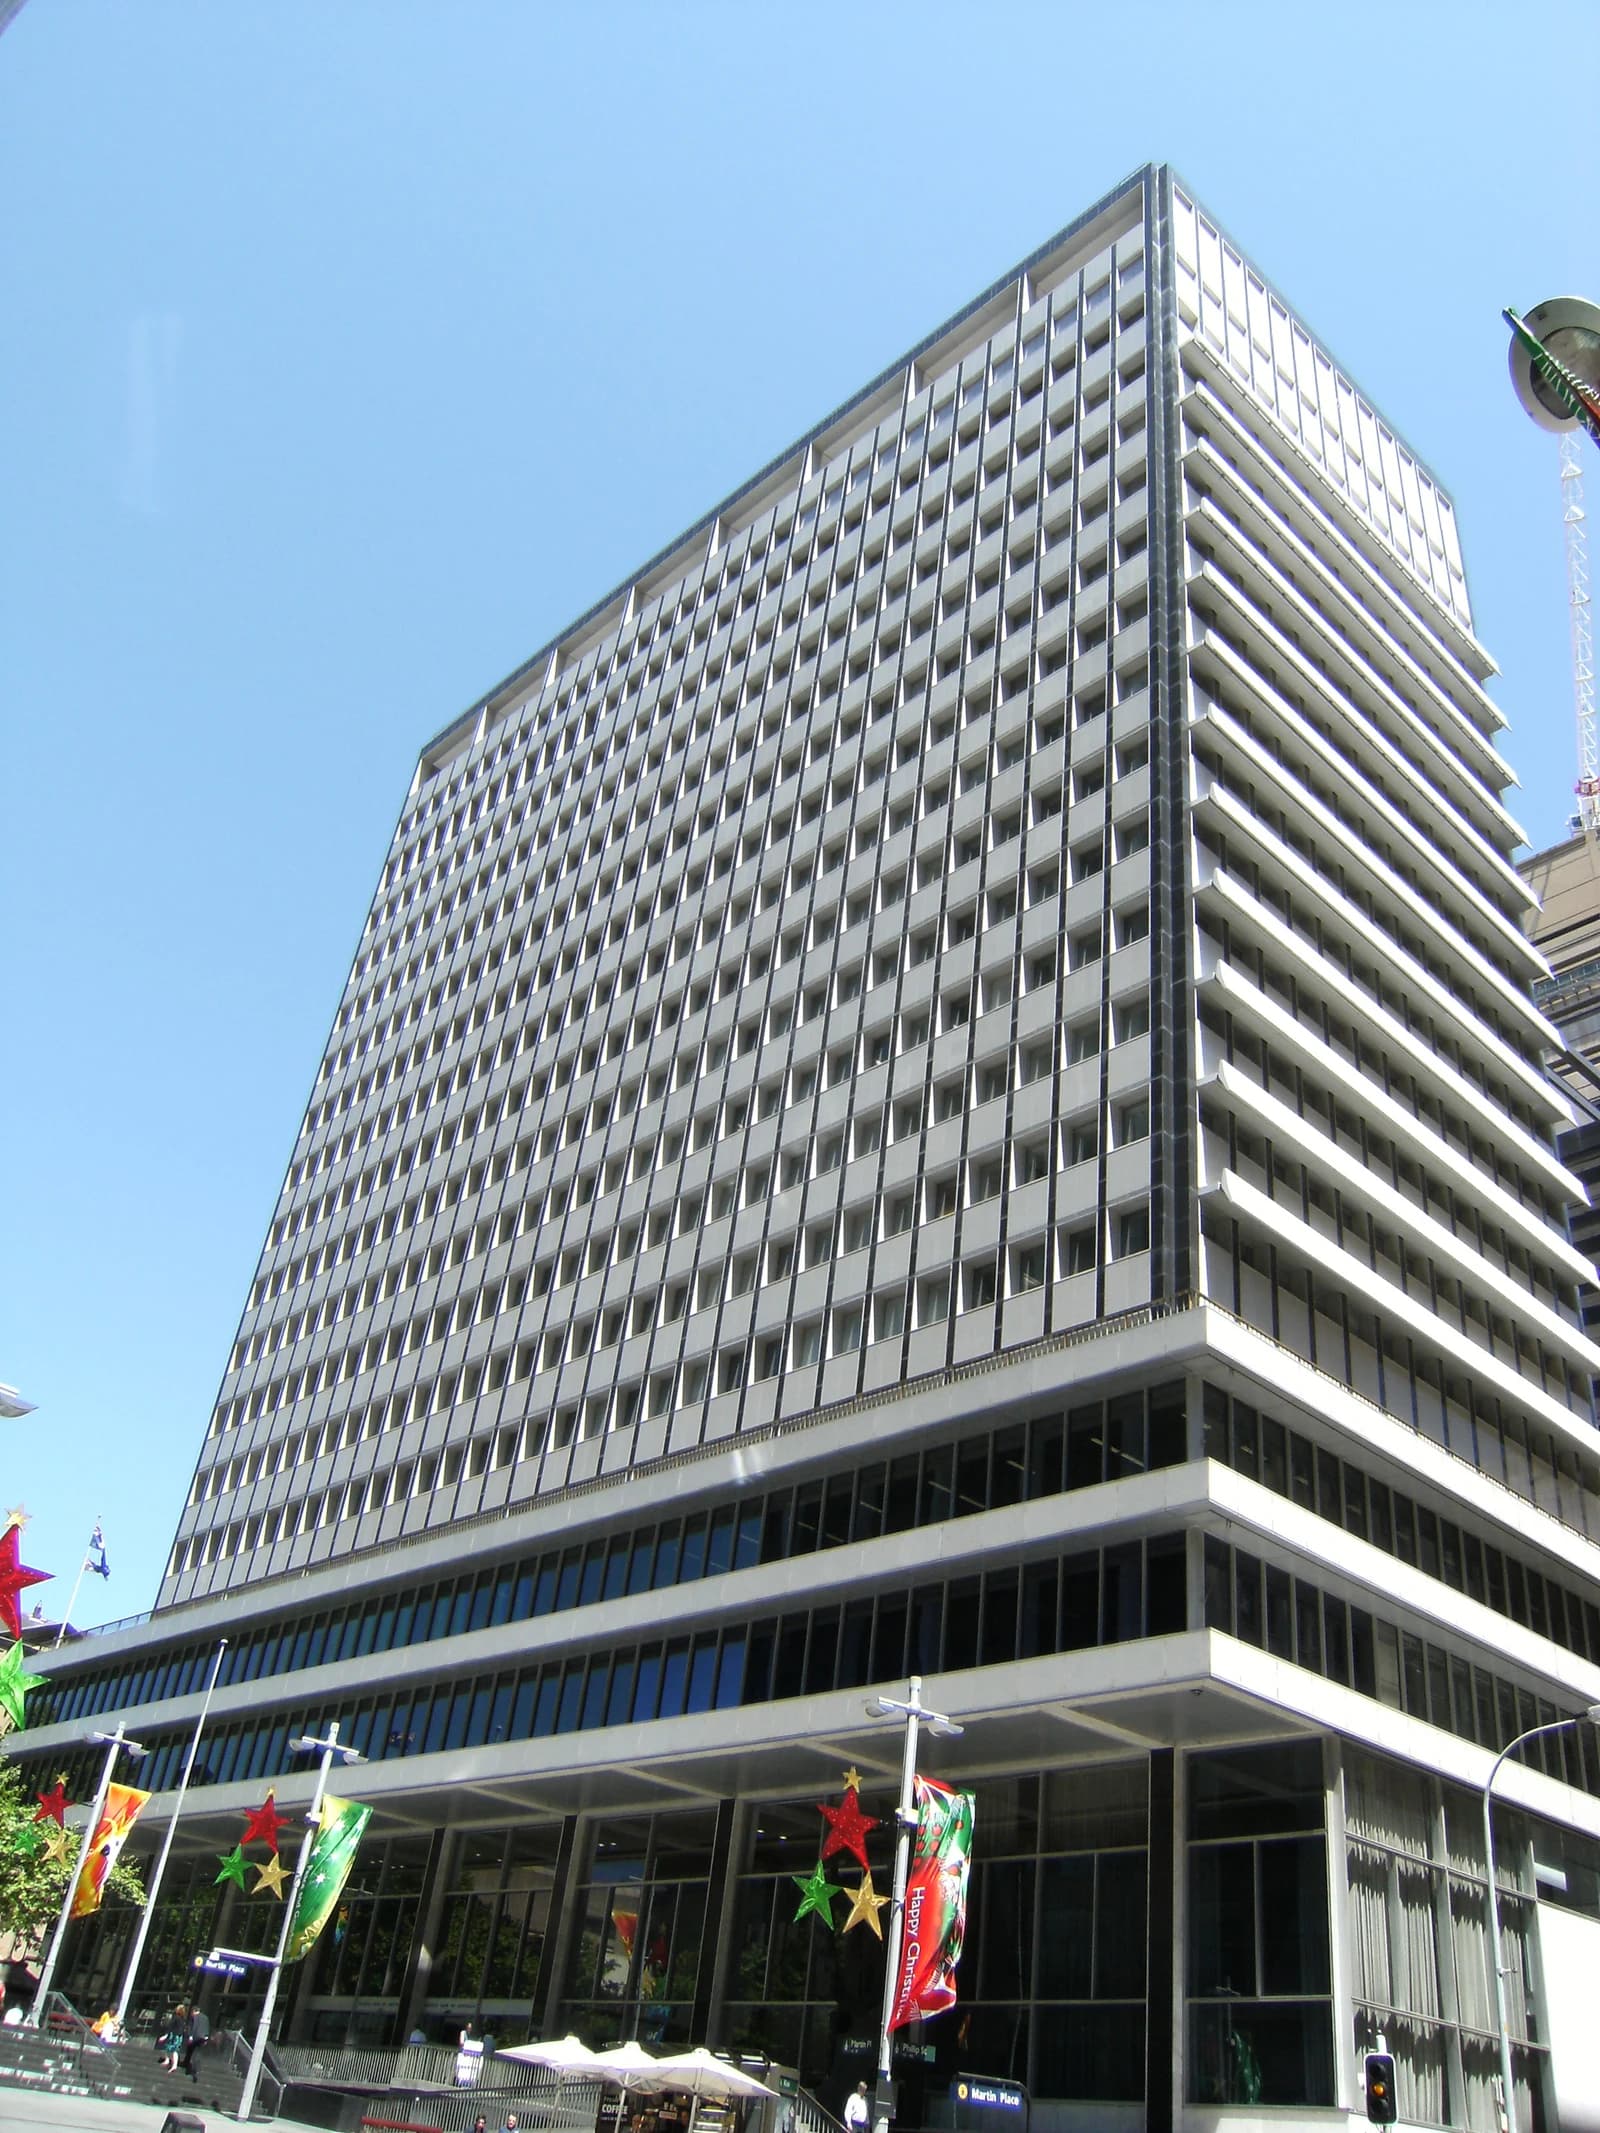
The call matters because the Reserve Bank of Australia is being told, in effect, that premature easing could undo the work already done to bring inflation back under control. With petrol prices climbing above $2.60 a litre amid tensions in the Strait of Hormuz, households are facing another hit to real incomes just as policymakers debate when relief can safely begin. That leaves the RBA with less room to respond to softer growth, and more reason to wait until inflation is clearly “dead,” as the seed headline puts it.
Sentiment IndicatorsⓘProprietary · adalytica.com · September 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the implications run beyond mortgage costs. A higher-for-longer rate path supports the Australian dollar relative to lower-yielding currencies, but it also keeps pressure on rate-sensitive sectors such as housing, retail and discretionary consumption. In Australia-listed equities, that tension is visible in exchange-traded fund flows and pricing: the iShares MSCI Australia ETF, EWA, has recently traded around $28.49 after touching $30.43 in late August, while the Australian dollar ETF, FXA, has held near $70.45, reflecting the market’s continuing focus on policy divergence and commodity-linked resilience.
The broader macro backdrop is still difficult. Adalytica’s US inflation-target confidence gauge shows extreme fear around inflation credibility, a reminder that central banks globally remain sensitive to any re-acceleration in prices after the post-pandemic surge. In Australia, that concern is amplified by a cost-of-living squeeze that has become politically charged, with critics warning that fiscal policy has not done enough to restrain demand. Calls to curb government spending reflect a familiar central-bank argument: if fiscal policy stays loose while energy prices rise, monetary policy has to do more of the heavy lifting.
The bullish case for keeping rates high is straightforward. It helps anchor inflation expectations, protects the RBA’s credibility and reduces the risk of a stop-start cycle in which markets price cuts too early only to face renewed tightening later. The bear case is equally clear: prolonging restrictive policy into a weaker growth patch could deepen household stress, weigh on leverage-heavy sectors and increase recession risk, especially if imported energy shocks persist.
For now, the message to markets is that any move toward cuts is likely to be delayed until the inflation trend is unmistakably broken. That keeps Australian bond yields, the currency and bank funding costs in focus, while leaving consumers to absorb more of the adjustment.
| Entity | Gains | Losses |
|---|---|---|
| RBA | ▲Credibility on inflation | ▼Pressure to ease early |
| Savers / AUD bulls | ▲Higher yields, firmer currency | ▼— |
| Mortgage holders / consumers | ▲— | ▼Higher borrowing costs, weaker spending power |
| Retailers / housing-sensitive stocks | ▲— | ▼Slower demand, tighter credit |


