Sugar prices are climbing again as crop losses in Brazil, India and the European Union are pushing the world market toward a deeper supply shortfall, a shift that could keep food inflation sticky and reward investors in sugar-related assets over the long term.
Sugar Prices Rise on Brazil, India and EU Crop Losses
Green Pool Commodities now sees a global sugar deficit of 6.28 million tons in the 2026/27 season, about 3 million tons larger than its prior estimate. That matters because sugar is not just a pantry staple; it is a globally traded agricultural commodity that feeds directly into food costs, beverage pricing and, in many markets, ethanol economics. When the balance between supply and demand tightens this sharply, the market usually does not stay calm for long.
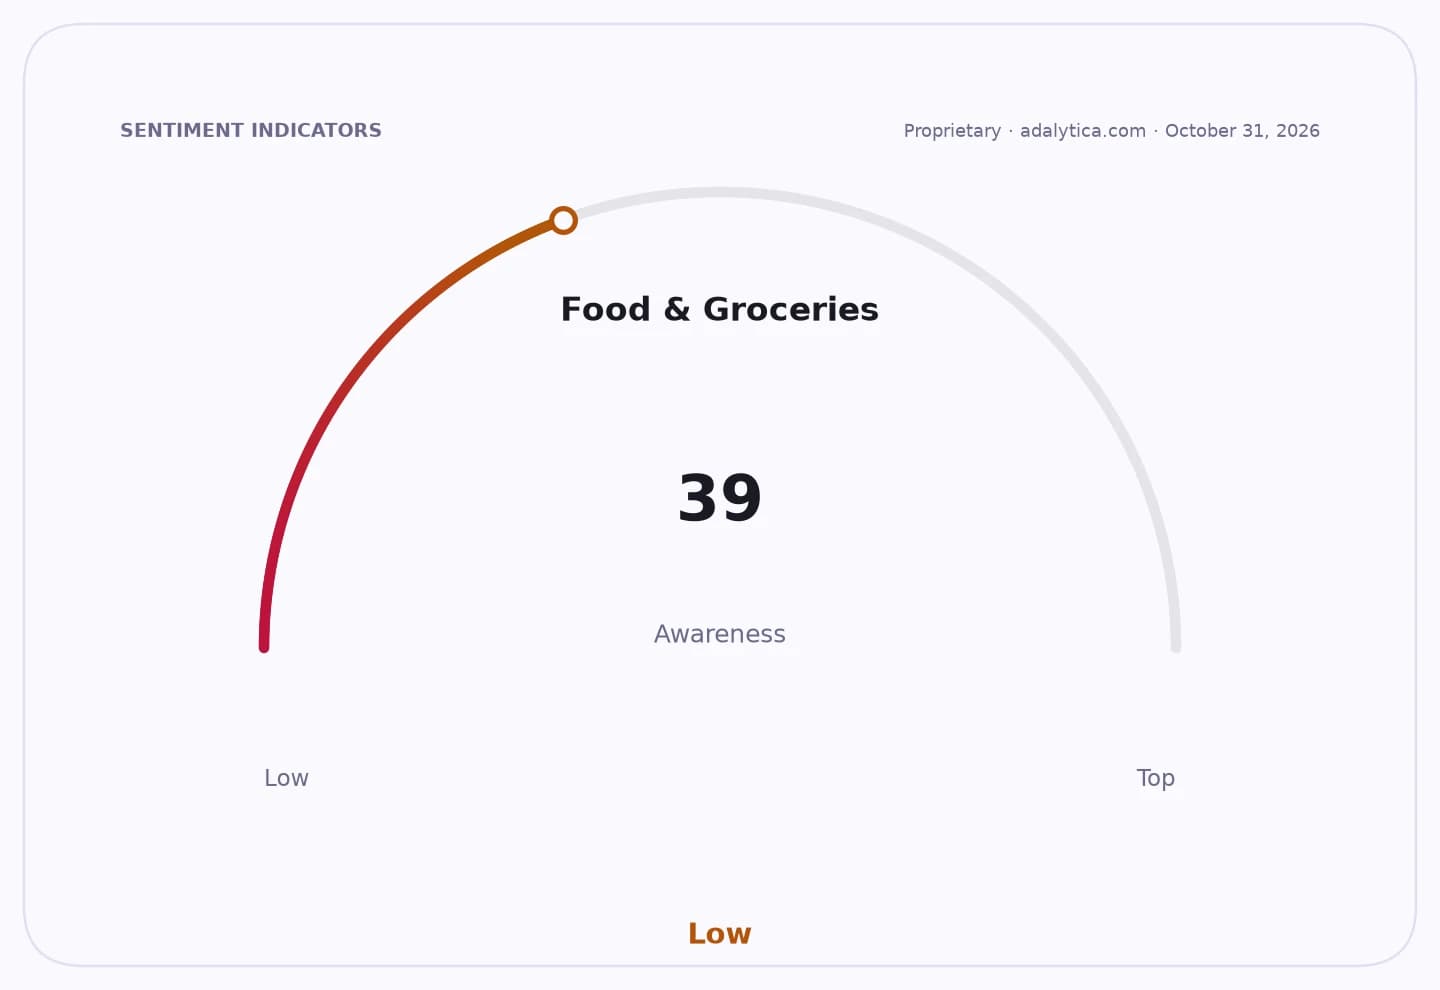
Sentiment Indicators
Food & Groceries
Brazil is the biggest reason. The country, the world’s largest sugar exporter, has seen center-south production undershoot expectations after heavy rains tied to El Niño hurt cane yields. By late September, Brazil’s cumulative sugar output was 14% below the level of a year earlier, according to the analyst. That kind of shortfall can quickly reduce export availability, and Brazil’s role in the trade makes every lost ton matter.
The picture is deteriorating elsewhere too. Green Pool cut its estimate for EU sugar production by 228,000 tons to 12.44 million tons after a hot, dry summer damaged crops. In India, officials allowed mills to start crushing the new crop earlier than usual to support thin domestic inventories, but that move may come at the cost of lower yields if cane has not matured fully. The analyst now sees Indian production down by 300,000 to 400,000 tons.
The price response has already started. Raw sugar recently rose to 21.29 cents a pound, the highest level in 19 months, as traders priced in tighter supply. For investors, that is the key takeaway: if the deficit forecast proves accurate, sugar-linked exchange-traded funds, commodity producers and exporters could stay supported, while food manufacturers, importers and consumers face higher input costs.
For long-term investors, this is a reminder that agricultural markets can move in multi-year cycles, not just on day-to-day headlines. Weather shocks, inventory levels and export flows can create big opportunities, but they can also reverse quickly if production rebounds. Sugar is worth watching, especially if you own broad commodity exposure or companies with meaningful sugar costs in their supply chain.
| Entity | Gains | Losses |
|---|---|---|
| Sugar producers/exporters | ▲Higher selling prices | ▼Weak harvests |
| Food and beverage makers | ▲— | ▼Higher input costs |
| Sugar-linked ETFs/investors | ▲Price momentum | ▼Volatility risk |
| Consumers/importers | ▲— | ▼More expensive sugar |