Slate Grocery REIT has filed and mailed its management information circular ahead of a special unitholder meeting to approve its acquisition by Brixmor Property Group and Everview Partners, putting the roughly $1.4 billion deal on the path to a shareholder vote.
Slate Grocery REIT files proxy for Brixmor takeover vote
The filing is the key step that moves the transaction from agreement to execution, giving investors a formal look at the terms and the process before the deal can close. For holders of Slate Grocery units, the vote will determine whether they take cash out of a grocery-anchored retail portfolio at a time when capital is still selective and financing costs remain elevated.
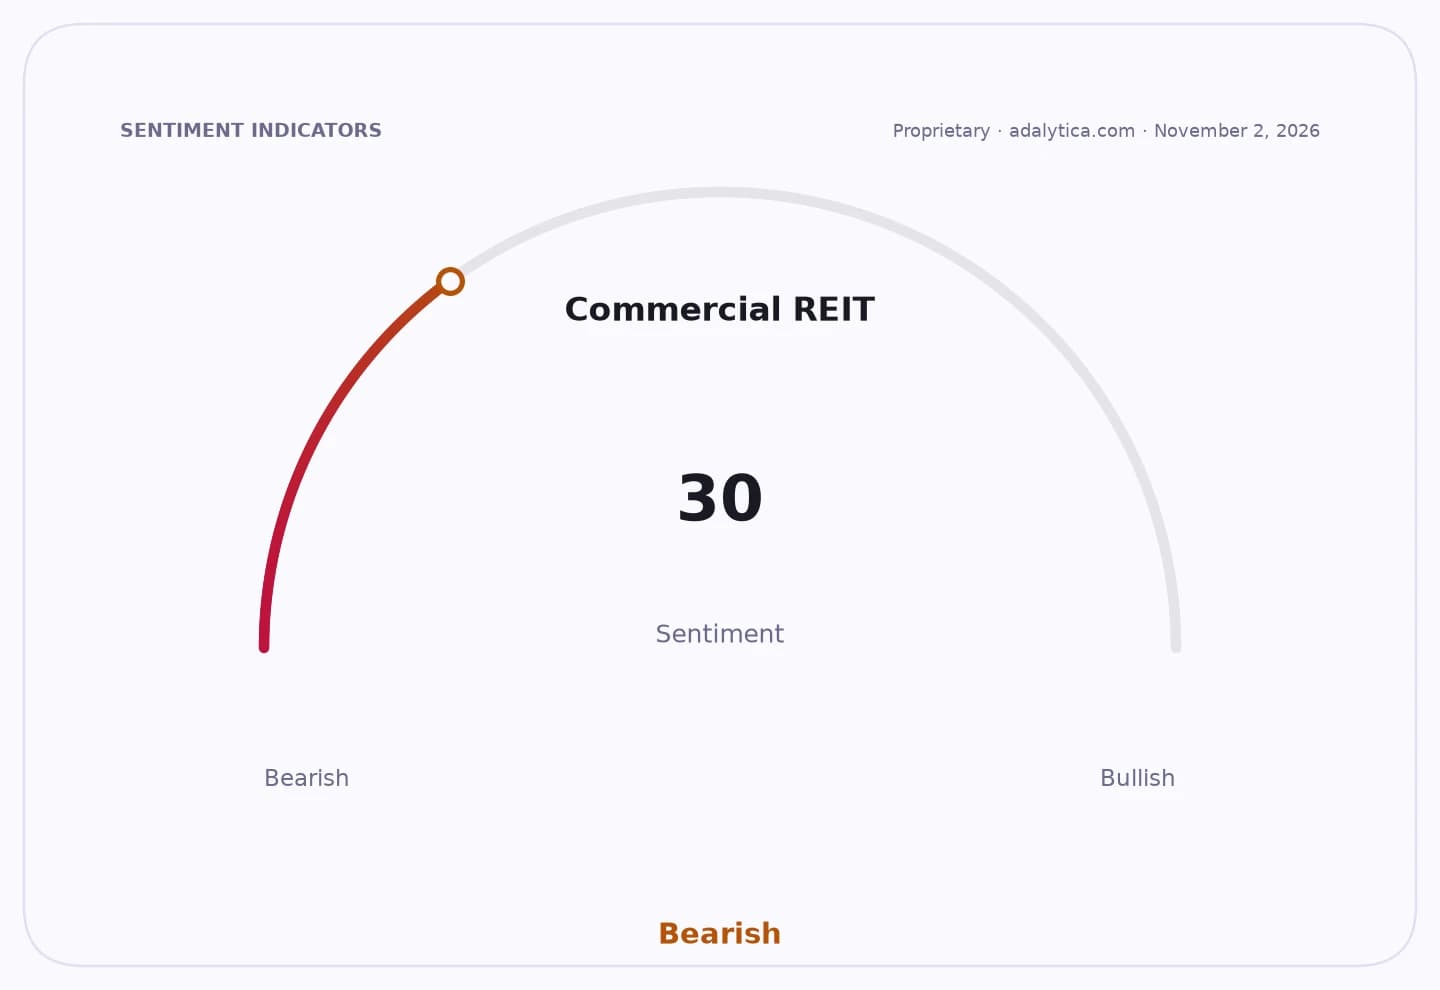
Sentiment Indicators
Brixmor has already disclosed the pending Slate transaction in its own filings, underscoring that the deal is part of a broader joint-venture structure with Everview. That matters because grocery-anchored shopping centers have remained one of the more defensive corners of retail real estate, attracting buyers looking for stable rent rolls and resilient traffic even as higher rates pressure valuations across the sector.
The backdrop is still important for pricing and investor appetite. The 10-year U.S. Treasury yield has been hovering around 4.95%, while high-yield credit spreads have widened to about 3.37 percentage points, a mix that keeps acquisition financing more expensive than in the low-rate years and helps explain why strategic buyers are favoring structured deals and asset portfolios with predictable cash flow.
Brixmor’s shares have been trading near 29.56, above its 200-day moving average of 29.04 and well above the 50-day average of 28.06, while its RSI reading of 74.3 points to stretched momentum. That suggests investors are already pricing in the benefits of acquisitions and portfolio expansion, but also leaves the stock vulnerable if the Slate process runs into delays or if financing terms tighten further.
For Slate unitholders, the next catalyst is the special meeting and the vote itself; for Brixmor and Everview, the main risk is whether the transaction closes on schedule and at the expected economics. If approved, the deal would add scale to Brixmor’s grocery-anchored platform and reinforce the market’s preference for defensive retail assets over more cyclical property types.
| Entity | Gains | Losses |
|---|---|---|
| Slate Grocery REIT unitholders | ▲Cash exit at deal price | ▼Independent upside if retail rebounds |
| Brixmor Property Group | ▲Grocery-anchored scale | ▼Integration and financing risk |
| Everview Partners | ▲Joint-venture foothold in retail REITs | ▼Capital committed to the deal |
| Competing REIT bidders | ▲Less access to Slate assets | ▼Fewer acquisition opportunities |