Used-car retailers are under pressure as signs build that buyers in key markets are becoming more price sensitive, with lower sticker prices, incentive-heavy launches and a broader push toward affordable models weighing on the economics of reselling vehicles.
CarMax, Penske, Lithia Face Used-Car Margin Pressure
That matters because the used-car business depends on a spread between acquisition cost and retail price. When new-car affordability improves, trade-in values and wholesale pricing can soften, leaving dealers with less room to earn gross profit on each unit. For companies such as CarMax, Penske Automotive Group and Lithia, even modest changes in vehicle pricing can ripple through margins, inventory turns and financing income.

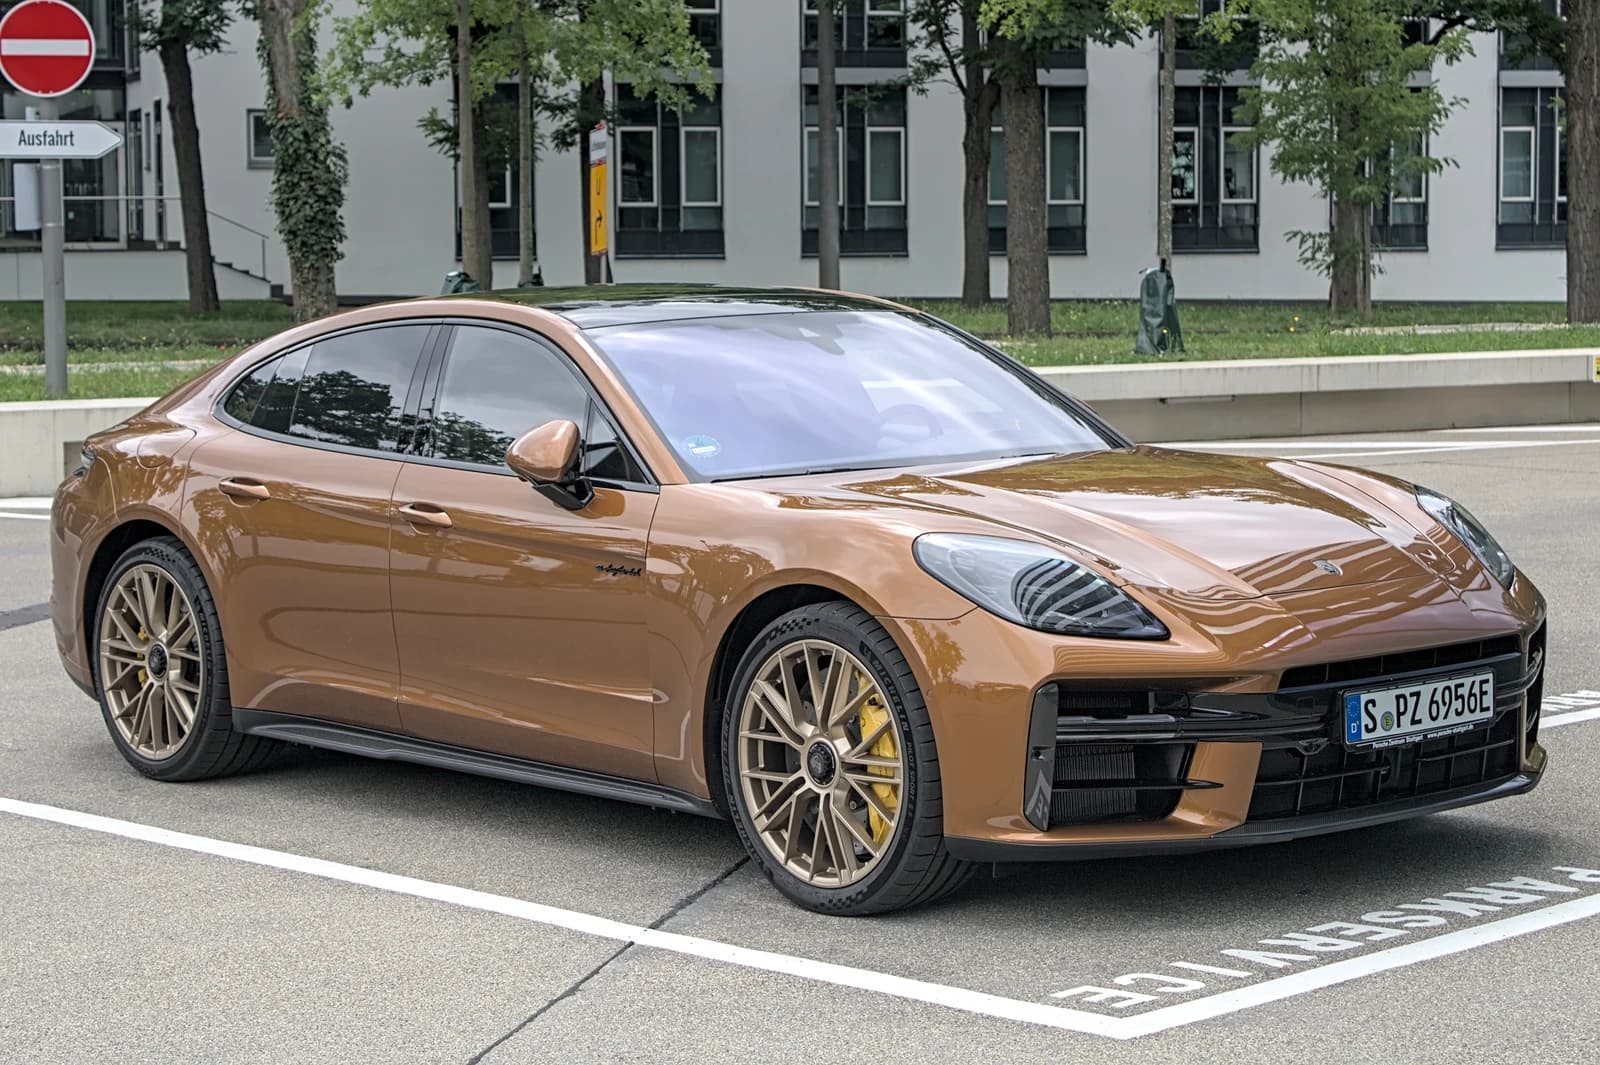
The seed headline points to the same dynamic: a wide range of models, from Suzuki Swift and Hyundai Tucson to BMW 5 Series, Porsche Panamera and Mercedes E-Class, underscores how broad the pricing battle has become across the market. In Pakistan, Toyota’s published 2026 prices show mass-market models such as the Corolla at PKR 6.169 million and the Aqua at PKR 4.5 million, while premium imports still command far higher tags, illustrating the gap dealers must navigate between accessible entry vehicles and high-end discretionary purchases.
In Southeast Asia, the upcoming Kia Soluto launch at about 46 million dong is aimed at first-time buyers, while competitors are leaning on budget EVs and fuel-efficient cars. That mix is significant for investors because it suggests demand is shifting toward lower-priced cars with less pricing power, a trend that can compress margins not only for new-car sellers but also for used-car platforms that rely on healthy residual values.

The market backdrop is already reflected in share performance and technical readings. CarMax has rebounded sharply from last year’s lows but has recently slipped back toward its 50-day and 200-day moving averages, with its relative strength index easing from overbought levels. Penske Automotive has been more resilient, but its recent price action also points to fading momentum after a strong summer run. Lithia remains the most volatile of the group, with big swings in both directions as investors reprice the pace of used-vehicle normalization.
The bull case is that cheaper cars can bring more buyers into showrooms, stimulate turnover and support service and financing revenue. Dealers with strong sourcing, reconditioning and omnichannel capabilities may still defend margins even if retail prices soften. The bear case is that lower transaction prices, especially in a market already dealing with higher competition and more transparent pricing, can squeeze gross profit per vehicle faster than volume improves.
For investors, the key question is whether affordability gains in new and used cars are a sign of healthier demand or the beginning of a further reset in pricing power. If consumers keep moving toward lower-priced models, dealers may need to lean harder on finance and aftersales income to protect earnings. That makes inventory discipline, sourcing efficiency and capital allocation more important than ever over the next several quarters.
| Entity | Gains | Losses |
|---|---|---|
| Car buyers | ▲Lower sticker prices | ▼Less urgency to buy now |
| Used-car dealers | ▲Higher traffic if volume rises | ▼Smaller gross margins |
| New-car makers | ▲Better affordability-led demand | ▼Weaker pricing power |
| Investors in KMX, PAG, LAD | ▲Potential volume support | ▼Margin compression risk |


