ASML’s surge back toward a record shows investors are still willing to pay up for the one company most exposed to the AI-capex supercycle, and the latest push into India is giving that story fresh geographic reach.
ASML Rises on AI Capex and India Expansion

The Dutch chip-equipment maker closed at €1,711.32 on Sept. 21, just below its recent highs and far above its 50-day moving average of €1,719.93, after a powerful climb from about €930 less than a year ago. For traders, the move is more than a chart breakout: it reflects the market’s view that advanced semiconductor spending is broadening rather than peaking. ASML sits at the center of that trend because its extreme ultraviolet lithography systems remain indispensable for the most advanced chips, and demand for those tools is ultimately tied to the buildout of AI servers, leading-edge logic and memory.
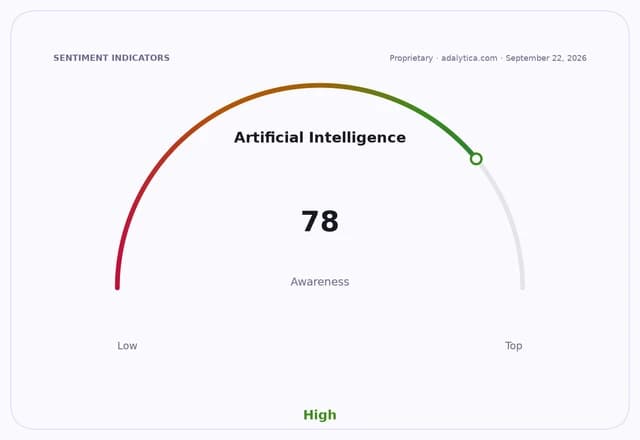
Sentiment IndicatorsⓘProprietary · adalytica.com · September 22, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The Indian expansion matters because it points to a longer runway for capex, not just a short burst of orders. ASML has begun operations in India as Tata Electronics builds out its semiconductor fabrication footprint, while New Delhi is trying to turn the country into a real node in the global chip supply chain. That widens the addressable market for ASML over time, especially as governments push domestic manufacturing, training and research alongside subsidy-backed industrial policy. In a sector where equipment suppliers live and die by multiyear spending cycles, any credible new geography is valuable.
ASML’s latest earnings only reinforce that thesis. The company said in July that second-quarter sales were €9.3 billion and lifted its 2026 revenue outlook to €43 billion to €45 billion, from a prior €36 billion to €40 billion range, while also raising its gross-margin target to 54% to 56%. That kind of guide-up is exactly what investors want to see when they are paying a premium multiple for structural growth. It suggests customers are still committing capital to advanced nodes even after a torrid run in chip stocks, rather than pausing for a digestion phase.
The broader semiconductor tape is confirming the same message. TSMC shares have climbed to $445.14, while Nvidia has rebounded to $227.38, keeping pressure on skeptics who expected AI infrastructure spending to cool faster. The sector is still digesting volatility, but the market is rewarding the companies that sit closest to the bottlenecks: chip designers on one end, foundry capacity on the other, and ASML in the middle as the toll road for next-generation manufacturing.
Technically, ASML’s recent recovery has also stabilized. Its relative strength index has moved back above 50, and the MACD has crossed toward positive territory, suggesting momentum is rebuilding after an earlier pullback. That does not make the stock cheap. It makes it powerful. When earnings are rising, orders are tied to secular AI capex, and new markets like India are opening up, expensive can stay expensive for a long time.
The takeaway for investors is straightforward: ASML remains one of the cleanest ways to own the AI infrastructure buildout without chasing the most crowded names. If the semiconductor capex cycle keeps extending, the market may be underestimating just how much operating leverage sits in ASML’s model. Pullbacks are likely to be bought, and the next leg higher could come as India’s chip ecosystem starts turning policy promises into actual equipment orders.
| Entity | Gains | Losses |
|---|---|---|
| ASML | ▲More EUV demand, higher margins | ▼Short sellers, valuation skeptics |
| TSMC | ▲Better equipment access, foundry expansion | ▼Capacity-constrained rivals |
| Nvidia | ▲Stronger AI buildout, more compute demand | ▼Investors betting on slowdown |
| India chip ecosystem | ▲Technology transfer, industrial growth | ▼Legacy manufacturing laggards |


