AmFIRST REIT’s plan to sell Menara AmBank for RM331 million is a decisive move to cut exposure to a low-yielding Kuala Lumpur office tower and recycle capital into assets with better return potential.
AmFIRST REIT to sell Menara AmBank for RM331 million
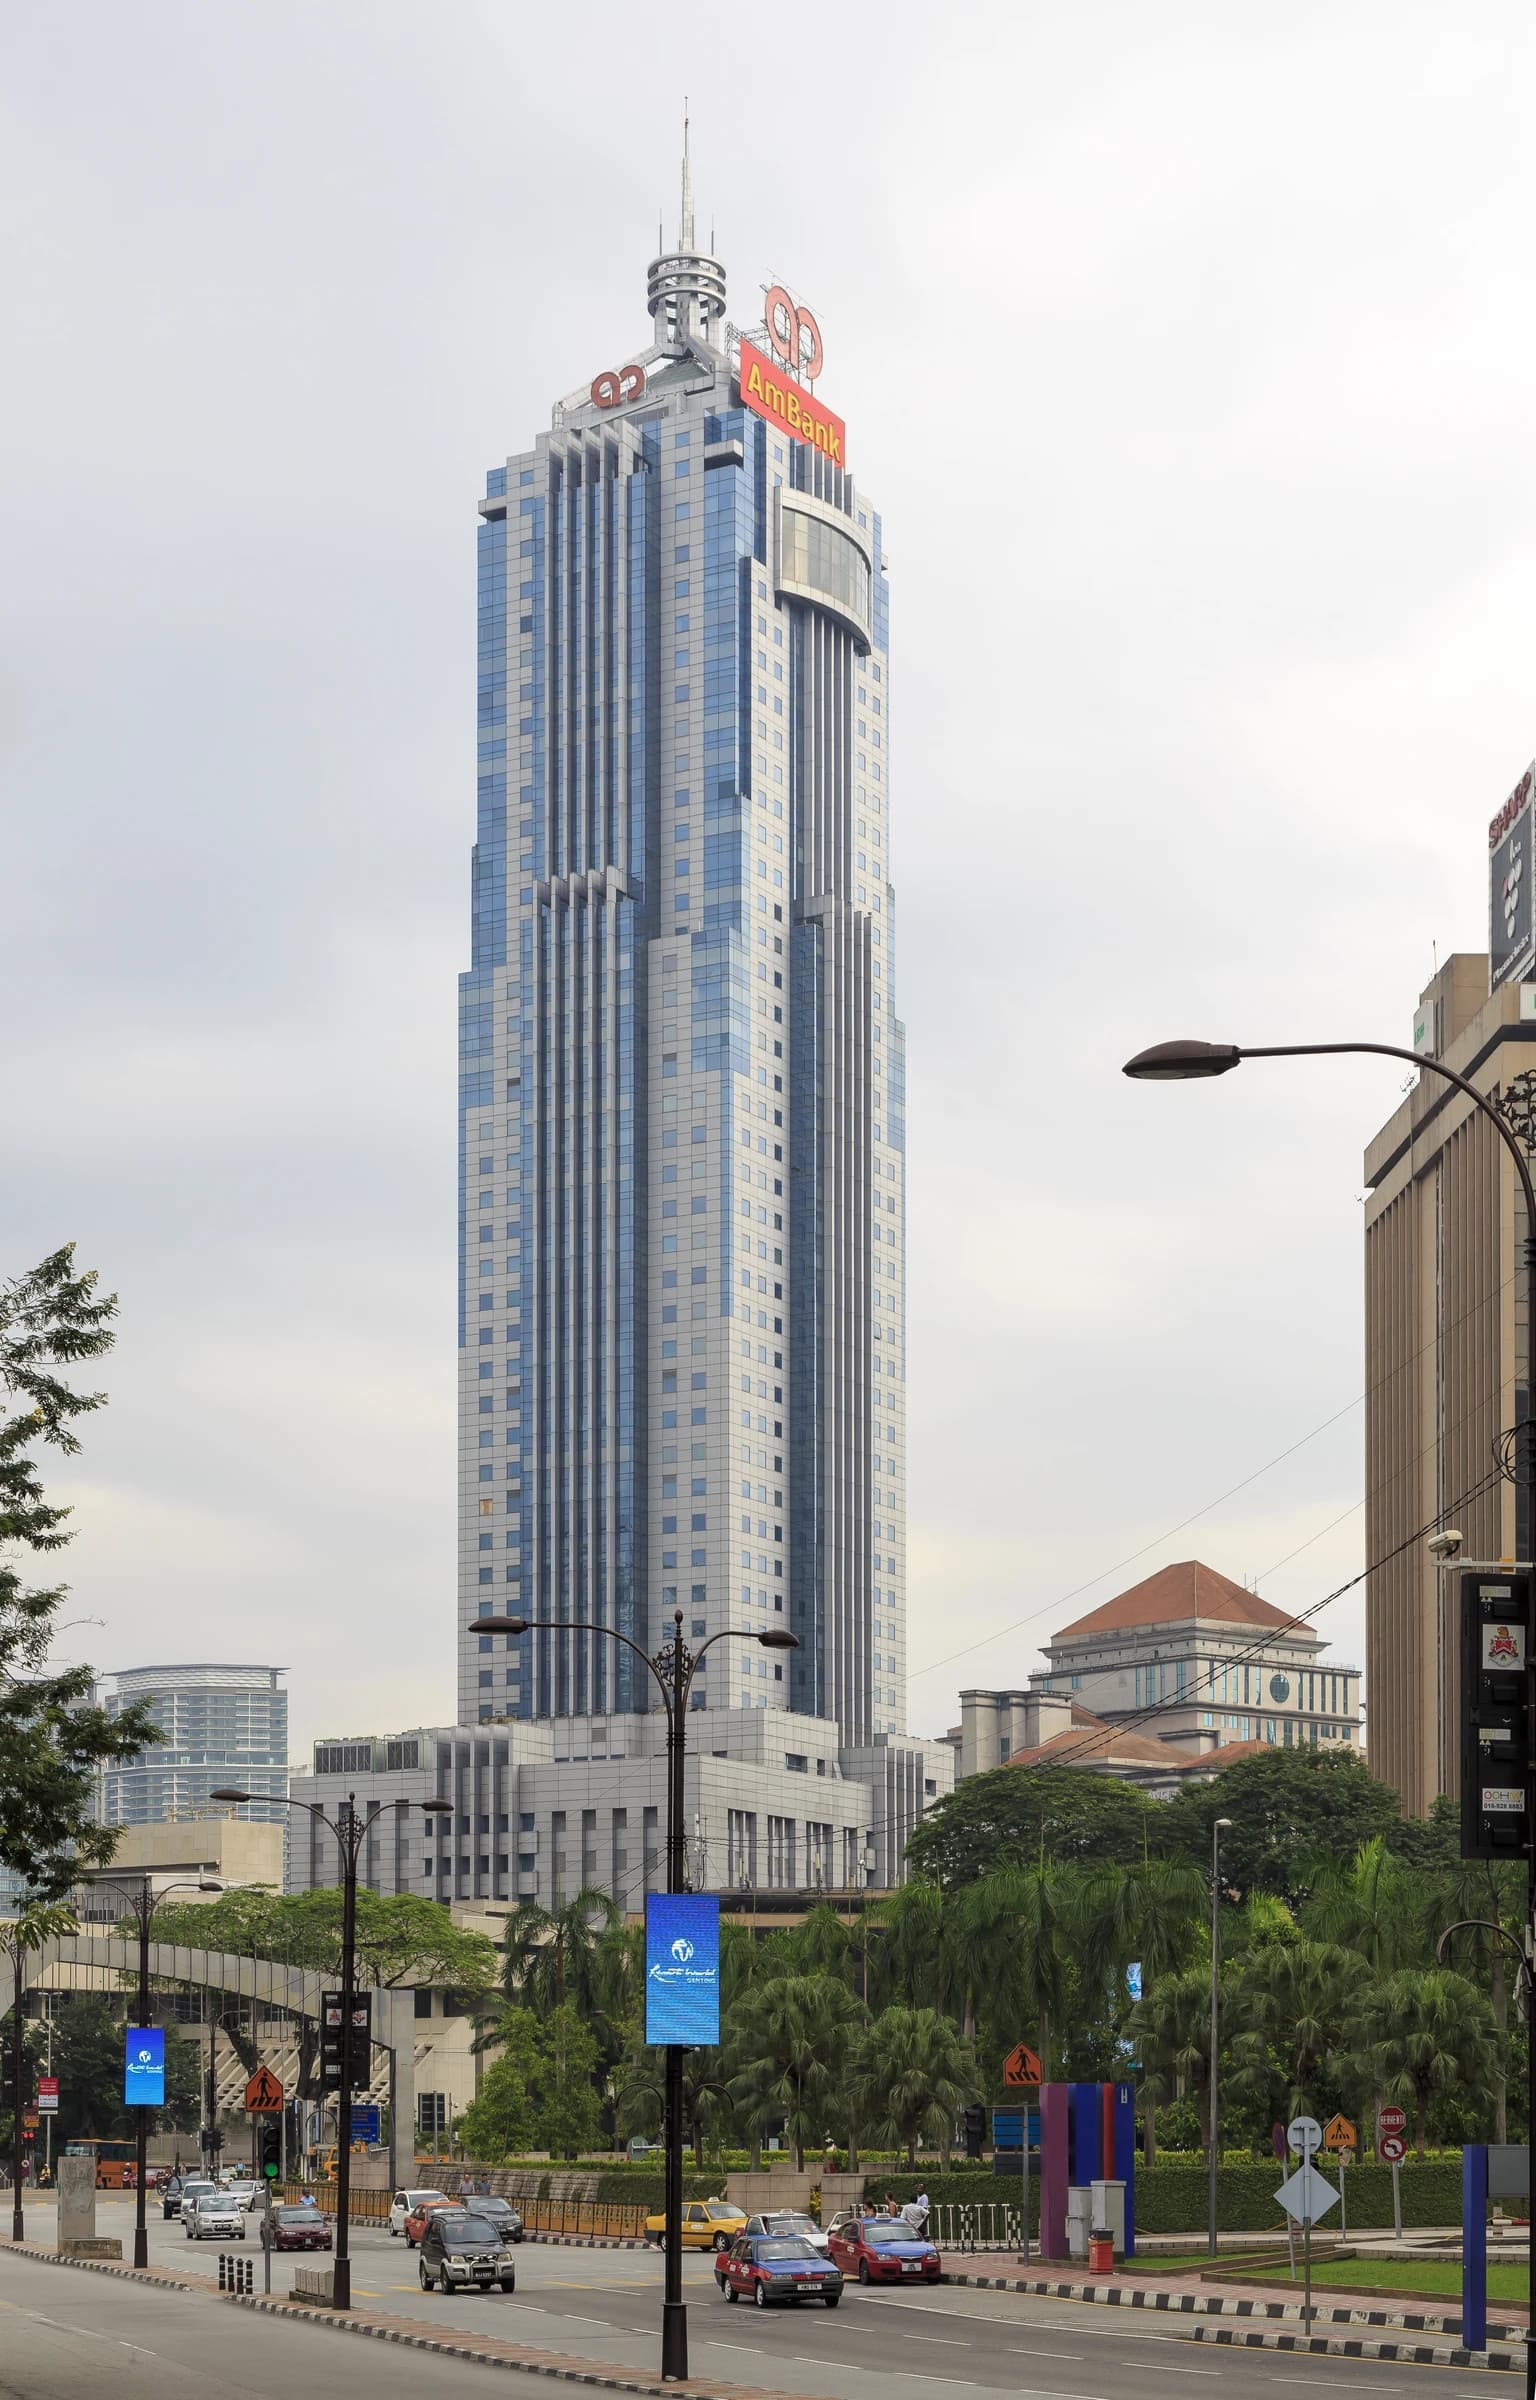
That matters because the deal shows how office landlords in Malaysia are being forced to confront a structural problem the market has been pricing in for years: oversupply, muted rental growth and weak occupancy are making some prime-looking towers poor earners. AmFIRST said Menara AmBank has generated persistently low net property income over the past decade, with average occupancy of 76.09% and limited scope for a meaningful uplift because of competition from newer, higher-spec buildings in the capital. In other words, the asset may sit in a prestigious address, but it is not producing the cash flow that justifies its capital tie-up.

For investors, the transaction is about more than one building. It is a test of whether a REIT can actively manage its portfolio rather than simply collect rent and wait for a market rebound. AmFIRST said the sale is part of a broader strategy to rationalize and diversify its holdings, dispose of low-return assets and redeploy capital into asset enhancement and higher-yield acquisitions. That is the right playbook in a sector where balance-sheet efficiency increasingly matters more than trophy addresses.
The economics of the deal also explain why the market should pay attention. Although AmFIRST expects a net disposal loss of about RM8.72 million, it also sees a gross capital gain of roughly RM61.67 million based on its updated investment cost, and a net capital gain of RM50.71 million after disposal expenses. Those figures suggest the trust is prioritizing long-term portfolio quality over short-term accounting optics. The sale could free up capital for assets that better support distributable income, which is ultimately what REIT holders care about.
There is also a related-party angle, since the buyer is AmBank (M) Berhad and the transaction involves Maybank Trustees Berhad as trustee for AmFIRST. That means unitholders will need to approve the deal before completion, expected in the first quarter of 2027 if all approvals are secured. For income investors, the key question is not just whether the sale closes, but whether management can prove the recycled capital earns a meaningfully higher return than Menara AmBank ever did.
My view is that the market underestimates how important this kind of capital reallocation is for REIT performance in a higher-for-longer rate environment. REITs that can shed weak office assets and pivot toward better-yielding, more diversified income streams deserve a valuation premium. AmFIRST is positioning itself for that transition, and investors should watch whether this sale becomes the first step in a broader reshaping of the portfolio.
| Entity | Gains | Losses |
|---|---|---|
| AmFIRST REIT | ▲Capital recycling | ▼Low-yield office exposure |
| AmBank (M) Berhad | ▲Ownership of core office asset | ▼Cash outlay |
| Unitholders | ▲Potential higher future returns | ▼Short-term disposal loss |
| Kuala Lumpur office peers | ▲Benchmark for portfolio cleanup | ▼Pressure on older towers |


