Western Australia’s FOB alumina price has climbed to $394 a ton, creating a nearly 693-yuan premium over China’s domestic index and underscoring how tight the seaborne market has become for a critical input to aluminum production.
Alumina Price Rises to $394 a Ton in Western Australia
That gap matters because alumina is the refinery product that sits between bauxite and aluminum, and a widening spread usually forces Chinese smelters and traders to choose between paying up for imports or leaning harder on domestic supply. With freight included, the imported price into major Chinese ports works out to about 3,338.86 yuan a ton, according to SMM data, a level that leaves little room for relief if spot demand stays firm.
Sentiment Indicators
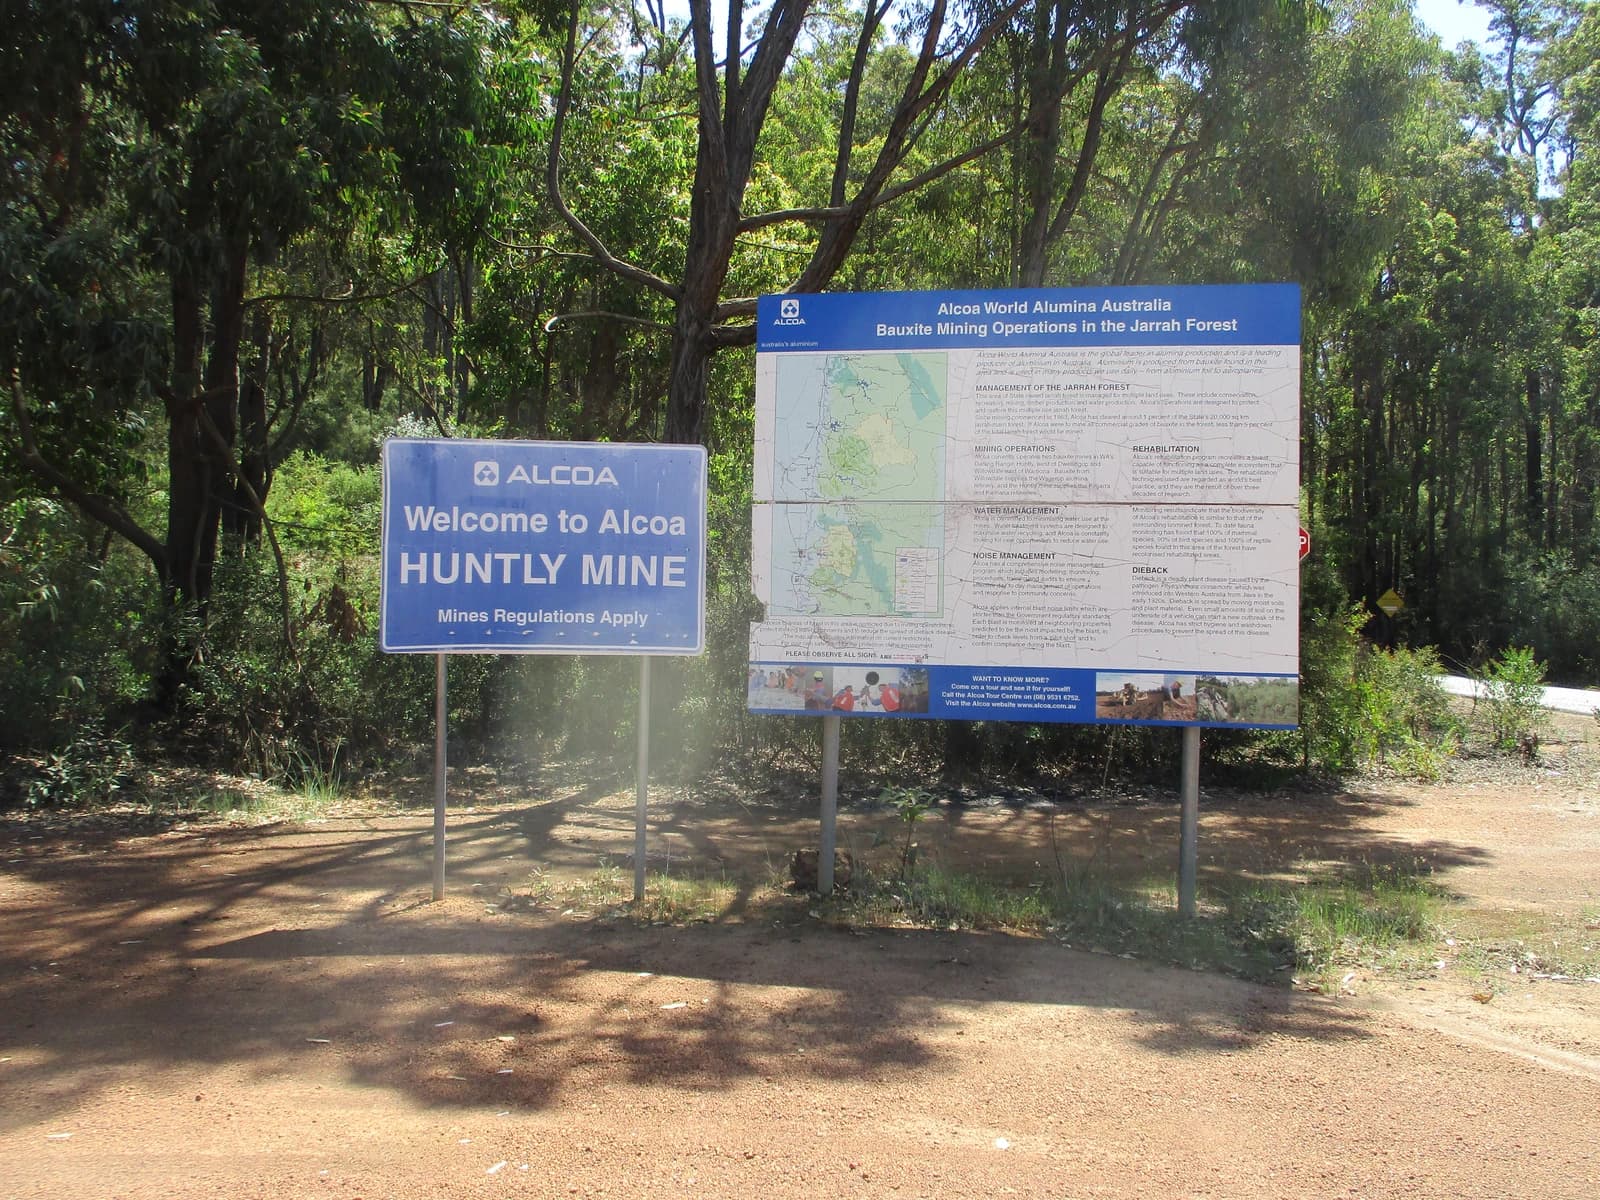
For investors, the message is clear: the market is underestimating how quickly raw-material inflation can feed through the aluminum chain. Higher alumina prices can support margins for upstream producers and exporters while squeezing downstream processors that lack pricing power. That is especially relevant for global aluminum names such as Alcoa, where alumina is a key earnings lever, and for China-linked producers facing a tougher cost base if imported material remains more expensive than domestic alternatives.
The move also fits a broader commodities backdrop in which energy volatility is helping keep industrial input costs elevated. Crude oil has surged above $100 a barrel in recent trading, and the weaker U.S. dollar backdrop is reinforcing the appeal of hard assets, including industrial metals. Adalytica’s global stability gauge sits at “Extreme Greed,” while its U.S. dollar trade signal shows “Extreme Fear,” a combination that tends to favor commodity pricing power and resource equities.
The equity reaction has been mixed, but the setup is increasingly attractive for investors who want exposure to the aluminum cycle before earnings fully catch up. Alcoa’s shares have been volatile and remain well below their recent highs, while smaller alumina-linked names such as Aluminum Corporation of China have also been knocked around, suggesting the market has not fully priced in sustained feedstock inflation.
If alumina stays above domestic Chinese benchmarks, the next catalyst is likely to be margin re-rating across the aluminum supply chain rather than a simple spot-price trade. That makes the best opportunity the producers with low-cost assets and direct exposure to rising alumina realizations, while the most vulnerable names are smelters and fabricators forced to absorb higher input costs. In this market, staying early matters.
| Entity | Gains | Losses |
|---|---|---|
| Western Australia alumina exporters | ▲Higher realized prices | ▼None |
| Alcoa (AA) | ▲Upstream pricing leverage | ▼Volatile downstream demand |
| Aluminum Corporation of China (ACH) | ▲Domestic supply optionality | ▼Higher import parity cost |
| Chinese smelters/fabricators | ▲— | ▼Squeezed margins |