Aixtron’s latest earnings have convinced JPMorgan the chip-equipment maker’s recovery is intact, even as the bank trims its target price to 52.50 euros from 54 euros on a change in valuation method.
Aixtron JPMorgan cuts target to 52.50 euros
That matters because Aixtron sits at the center of two of the most investable growth themes in semiconductors: optoelectronics and power devices. JPMorgan’s message is not that the business is weakening — it is that the market may still be underpricing the durability of demand for equipment used in gallium nitride, or GaN, and silicon carbide, or SiC, both critical to electric vehicles, fast charging, industrial power and next-generation optical applications.
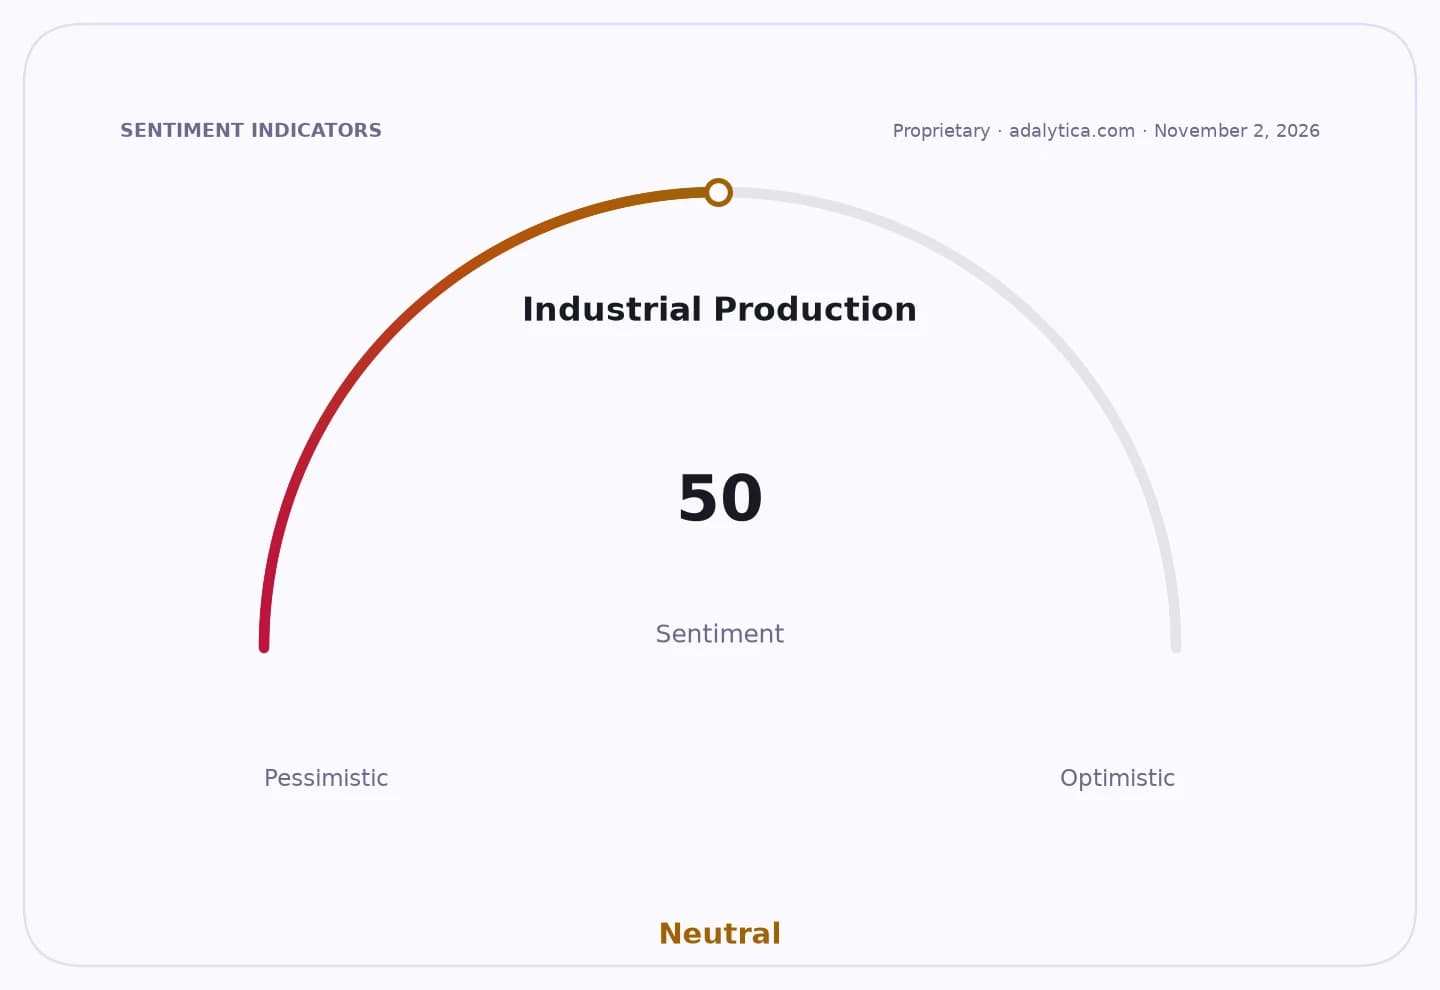
Sentiment Indicators
Craig McDowell said the quarterly results reinforced his bullish stance, arguing the optoelectronics cycle is becoming “larger and more sustainable” while GaN and SiC business is recovering. In other words, this is not just a cyclical bounce; it is a broader capex upcycle tied to the electrification and AI infrastructure build-out that is still filtering through the semiconductor supply chain.
The stock has already moved far ahead of its recent lows, and that is exactly why the valuation debate matters. Aixtron closed at 33.66 euros on Monday, well below JPMorgan’s target, but the shares remain volatile after a sharp run earlier in the year and then a steep pullback. The 50-day moving average sits above the current price, while the 200-day moving average is higher still, underscoring how much of the year’s rerating has been given back. For investors, that creates a classic setup: a high-quality capital equipment name with an analyst still calling for outperformance, but with expectations reset enough to offer another entry point if the recovery in compound semiconductor spending continues.
The broader read-through extends beyond Aixtron. If GaN and SiC demand is improving, that supports the case for a more sustained rebound in specialty semiconductor tools, not just the megacap AI names dominating the trade. It also points to better conditions for suppliers exposed to power electronics, optical communications and advanced packaging, areas where customers have been uneven but where long-term investment needs are unmistakably rising.
The market should not mistake a lower target for a weaker thesis. JPMorgan’s revision appears methodological, not fundamental, and the underlying story is that Aixtron remains leveraged to a multi-year industrial upgrade cycle. If the optoelectronics buildout stays firm and GaN/SiC orders keep recovering, the stock could resume its rerating well before consensus fully catches up.
| Entity | Gains | Losses |
|---|---|---|
| Aixtron | ▲Higher conviction from JPMorgan | ▼Lower target price narrative |
| GaN/SiC suppliers | ▲Recovery in demand | ▼Buyers waiting for cheaper capex |
| Semiconductor equipment bulls | ▲Cycle confirmation | ▼Short-term valuation skeptics |
| Rivals in tools | ▲Sector tailwind | ▼Share gains if Aixtron wins orders |